 +44 20 3885 6670
 アメリカ合衆国Energy & PowerL#20261207
45MW Grid Power & 50MW Natural Gas Opportunity
A strategic development opportunity in t…
- 希望価格
- $16,000,000
- 売上
- 未確定
- EBITDA
- 未定
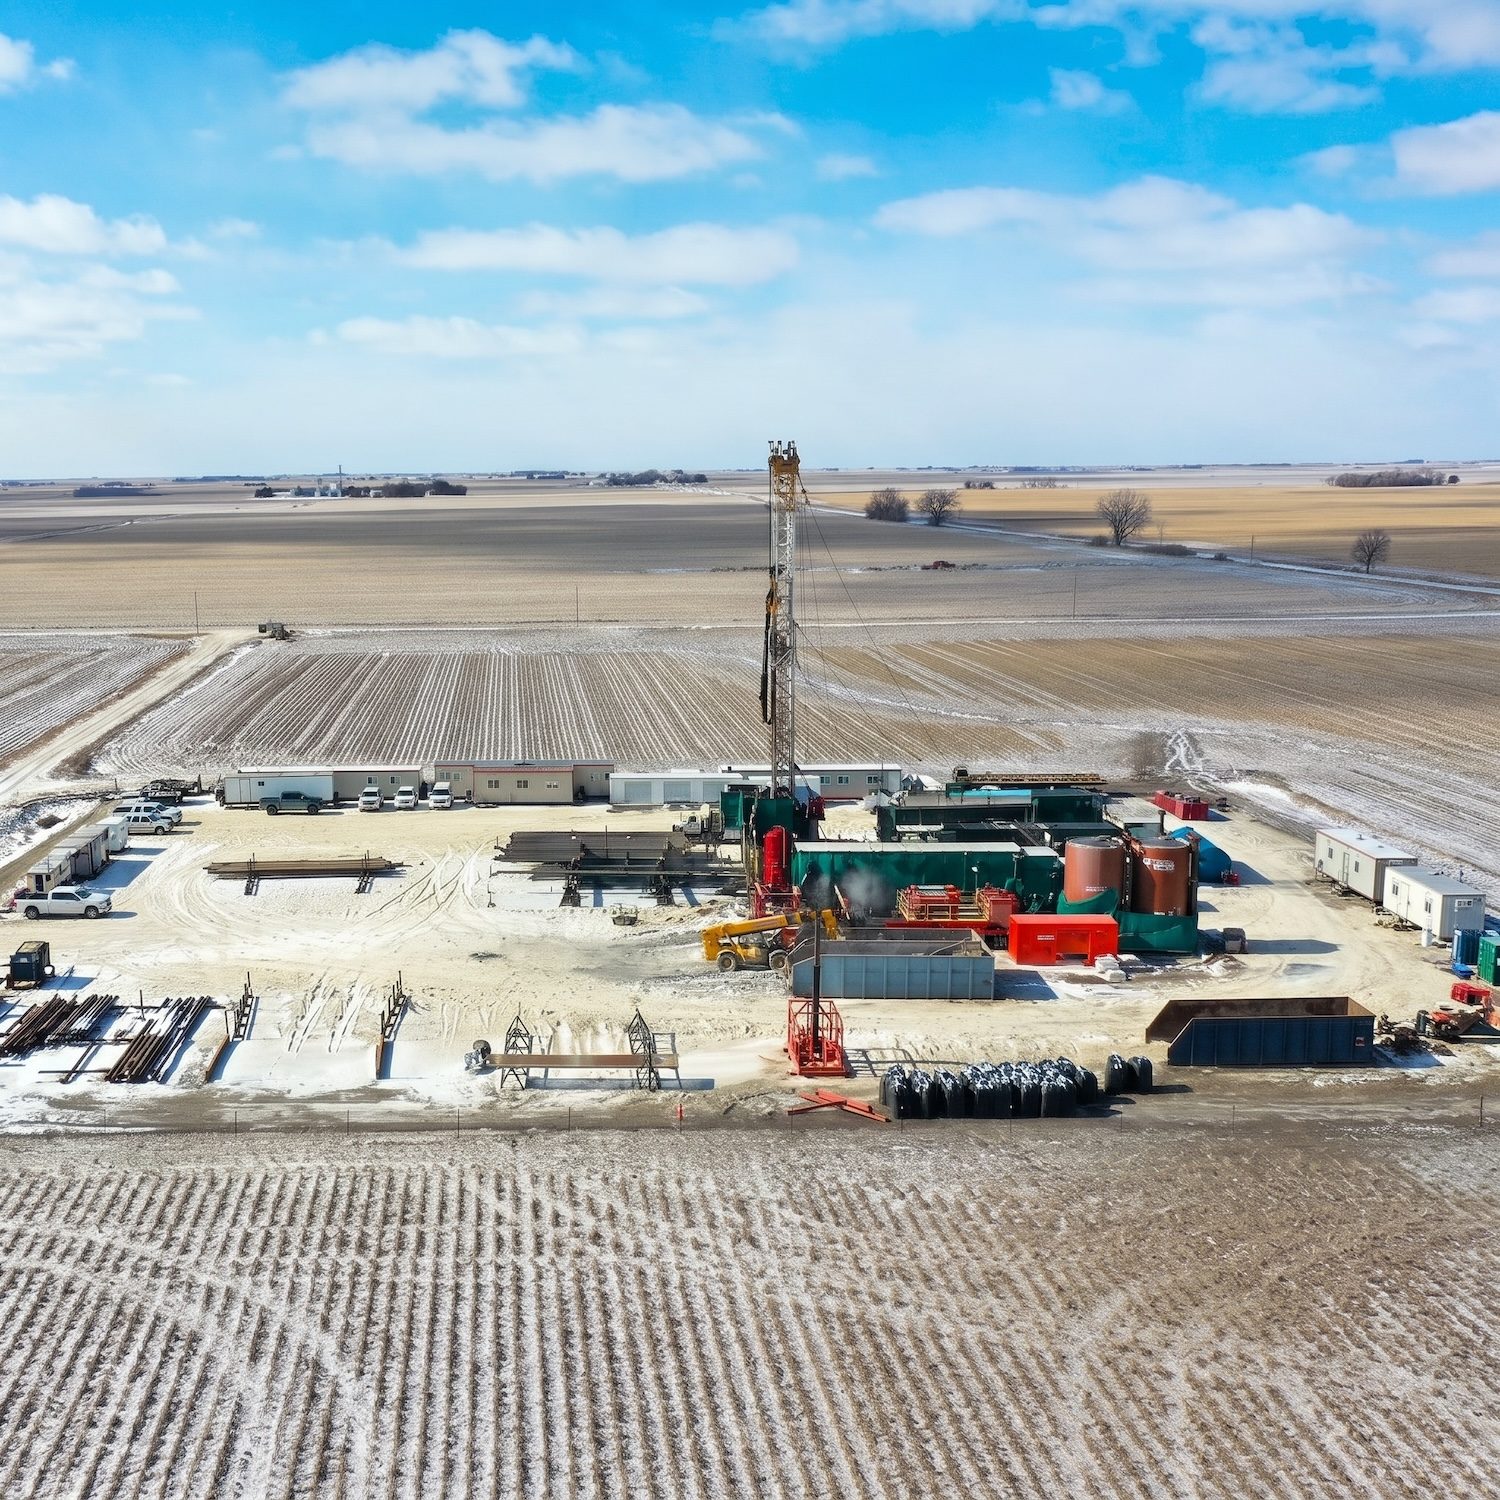
This project is an institutional pre-drill exploration program focused on delineating subsurface natural (geological) hydrogen and co-occurring strategic helium systems in the U.S. Gulf Coast basin (Texas). The sponsor is raising $13.5M in staged, milestone-gated capital over an 18 to 19 month exploration lifecycle to convert existing proprietary desktop reconnaissance into 1 to 2 substantiated, drill-ready subsurface targets. This structure isolates pre-drill geologic confirmation from downstream development risk, minimizing dry-hole exposure prior to full-scale drilling and plant capital deployment.
The venture’s proprietary predictive geological targeting is backed by direct historical operating leadership on the first benchmark U.S. natural hydrogen exploration well (drilled in Fillmore County, Nebraska in 2019), which logged high-grade wellhead gas tests of 44% hydrogen and 12.8% helium.
Natural geologic extraction yields an estimated production cost of $0.50 to $1.00 per kg of hydrogen with an ultra-low carbon intensity (~0.4 kg CO2e per kg of hydrogen), heavily outcompeting both green water-electrolysis ($4.50 to $12.00 per kg) and fossil grey SMR ($1.00 to $3.00 per kg) routes.
Helium demand in advanced semiconductor manufacturing, quantum computing, cryogenics, and aerospace creates an outsized revenue cushion. Modeled conservatively at an initial 2% concentration by volume and priced at a discount to spot, helium serves as a primary driver of project capital efficiency and early payback.
Texas provides clear administrative and mineral rights pathways (~1 month / ~$200K acquisition profile), competitive rig mobilization rates, and direct access to heavy industrial offtake clusters (refineries, ammonia, methanol, and chemical complexes) along Gulf Coast distribution corridors.
Pre-drill equity deployment is governed by technical decision gates, releasing capital only upon definitive geologic evidence:
| Gate / Phase | Duration | Capital | Primary Scope of Work | Unlocked Milestone |
| Gate 1: Target Selection | 3 to 4 months | $1.5M | Finalize desktop leads, rank prospective acreage, establish initial permitting frameworks. | Narrow asset portfolio to 3 to 4 Areas of Interest (AOIs). |
| Gate 2: Field Validity | 6 months | $3.0M | Mineral licensing across 2 AOIs; surface geochemical soil surveys to test gas migration pathways. | Prioritize 1 to 2 AOIs with confirmed surface anomaly signatures. |
| Gate 3: Drill Readiness | 9 months | $9.0M | 2D/3D geophysics, structural model refinement, shallow strat-hole drilling, FEED/permitting readiness. | Deliver 1 to 2 drill-ready structures prepared for exploration drilling financing. |
| Total Program | 18 to 19 months | $13.5M | Full pre-drill program prior to development-stage underwriting. | Drill-ready status achieved. |
The financial model below details an illustrative commercial exploitation scenario for one target structure under baseline Texas execution conditions against an upside regional benchmark, incorporating full extraction, separation, and purification surface infrastructure.
| Parameter | Texas Execution Case | California Benchmark Case | Basis / Source |
| Pre-Drill Equity Investment | $13.5M | $13.5M | Program de-risking raise |
| Commercial Facility CAPEX | $150.0M | $150.0M | Extraction, purification, separation plant |
| Construction Timeline | 4.0 Years | 4.0 Years | Engineering, procurement, construction |
| Annual Hydrogen Nameplate Output | 25.0 ktpa (25.0M kg) | 25.0 ktpa (25.0M kg) | High purity grade (99.999%) |
| Annual Helium Nameplate Output | 1.0 ktpa (1.0M kg) | 1.0 ktpa (1.0M kg) | Ultra-high purity (up to 7N grade) |
| Delivered Hydrogen Contract Price | $3.00 per kg | $5.00 per kg | Pipeline / regional delivery within ~20 km |
| Realized Helium Gate Price (EXW) | $90.00 per kg | $90.00 per kg | Significant discount vs. ~$150 per kg market spot |
| Direct Operating Cost (Hydrogen) | $1.00 per kg | $1.00 per kg | Subsurface natural lift + processing |
| Direct Operating Cost (Helium) | $8.00 per kg | $8.00 per kg | Separation & liquefaction/storage |
| Facility Operating Uptime | 97.0% | 97.0% | Base industrial plant availability factor |
| Discount Rate (Real) | 10.5% | 10.5% | Project weighted average cost of capital |
Reflecting 97% operational availability across both product streams:
| Line Item | Texas Execution Case | California Benchmark Case | Notes |
| Gross Hydrogen Revenue | $72.75M | $121.25M | Based on 24.25M kg sold |
| Gross Helium Revenue | $87.30M | $87.30M | Based on 0.97M kg sold |
| Total Net Revenue | $160.05M | $208.55M | Combined multi-gas stream |
| Direct Hydrogen Operating Costs | ($24.25M) | ($24.25M) | $1.00 per kg produced |
| Direct Helium Operating Costs | ($7.76M) | ($7.76M) | $8.00 per kg produced |
| Total Direct Operating Costs | ($32.01M) | ($32.01M) | Field extraction and processing opex |
| Steady-State EBITDA | $128.04M | $176.54M | Annual cash operating profit |
| EBITDA Operating Margin | 80.0% | 84.7% | High margin driven by helium co-production |
Reflecting a 4-year development and construction period followed by steady-state production:
| Line Item ($M) | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 (COD) | Year 6 | Year 7 | Year 8 | Year 9 | Year 10 |
| Pre-Drill Equity Tranche | ($4.50) | ($9.00) | — | — | — | — | — | — | — | — |
| Facility Construction CAPEX | — | — | ($75.00) | ($75.00) | — | — | — | — | — | — |
| Commercial Revenue (TX Base) | — | — | — | — | $160.05 | $160.05 | $160.05 | $160.05 | $160.05 | $160.05 |
| Operating Costs (TX Base) | — | — | — | — | ($32.01) | ($32.01) | ($32.01) | ($32.01) | ($32.01) | ($32.01) |
| Net Operating Cash Flow | ($4.50) | ($9.00) | ($75.00) | ($75.00) | $128.04 | $128.04 | $128.04 | $128.04 | $128.04 | $128.04 |
| Cumulative Net Cash Flow | ($4.50) | ($13.50) | ($88.50) | ($163.50) | ($35.46) | $92.58 | $220.62 | $348.66 | $476.70 | $604.74 |
| Valuation Metric | Texas Execution Base Case | California Upside Case | Sensitivity Notes |
| Net Present Value (NPV at 10.5%) | ~$300M | ~$500M | Driven by a +$2.00 per kg premium on hydrogen |
| Internal Rate of Return (IRR) | ~38% | ~52% | Robust downside buffer provided by helium sales |
| Discounted Payback Period (DPP) | ~6.7 Years | ~5.7 Years | Incorporates the 4-year development phase |
| Helium Revenue Contribution | 54.5% | 41.9% | Represents ~3.8% of product volume but over half of base revenue |
$13.5M technical exploration financing.
Project-level special purpose vehicle (SPV) / asset-level partnership covering the Texas perimeter.
Seeking a lead investor commitment of $3.5M+ to set board governance, pacing, and tranche clearance criteria, supported by participating co-investors and corporate strategics from $1.0M+.
| アドバイザー | Deals |
|---|---|
| MergersCorp M&A International | 21 |
| Keith Advisory | 17 |
| GCG | 9 |
| JP Morgan | 41 |
| Jefferies | 23 |
| Lazard | 26 |
| Goldman Sachs | 30 |
売却案件
アメリカ合衆国Energy & PowerL#20261207A strategic development opportunity in t…
 カザフスタンEnergy & PowerL#20261198
A portfolio of identified polymetallic m…
 カザフスタンEnergy & PowerL#20261199
An exploration-stage copper and associat…
 イタリアRenewable energyL#20261228
A 12.73 MWp agrivoltaic solar photovolta…
 アメリカ合衆国TechnologyL#20261226
A large-scale energy and data center dev…
 アメリカ合衆国TechnologyL#20261227
An opportunity to participate in a large…
 アメリカ合衆国TechnologyL#20261225
Astrategically positioned land and power…
 アメリカ合衆国TechnologyL#20261224
The project is structured around long-te…