 +44 20 3885 6670
 スペインBusiness ServiceL#20261223
20-Year-Old Regional English-Language Broadcaster (5x FM Frequencies)
The organization is a leading commercial…
- 希望価格
- $1,000,000
- 売上
- $480,000
- EBITDA
- 未定

 インド
An opportunity to acquire a fast-growing, founder-led Business Process Outsourcing (BPO) and Customer Experience (CX) company headquartered in India, serving domestic and international clients through a structurally low-cost Tier-2 delivery network.
The company has demonstrated consistent organic growth, increasing revenue from US$1.3 million in FY21 to US$18 million in FY26, achieving a 19.5% revenue CAGR between FY23 and FY26.
Its expanding client portfolio has significantly reduced customer concentration, with the largest client's contribution declining from 55% to 25% of total billing, while the number of billed clients increased from 18 to 52 over the past three years.
The business benefits from a differentiated operating model, supported by government-backed public-private partnership (PPP) delivery centres, enabling substantially lower occupancy costs, adjusted EBITDA margins of approximately 22%, and a highly capital-efficient operating structure.
Key Investment Highlights
Strong and Consistent Growth
Revenue increased from US$1.3M in FY21 to US$18M in FY26.
19.5% revenue CAGR between FY23 and FY26.
Five consecutive years of organic revenue growth.
Profit growth has consistently outpaced revenue growth.
Diversified and Resilient Client Portfolio
Largest client concentration reduced from 55% to 25%.
Top three clients account for approximately 58% of revenue, with concentration declining.
52 billed clients across multiple industries.
Core verticals include healthcare, social e-commerce, and banking/financial services, each growing 18–26% annually.
Recurring and Contracted Revenue
Multi-year contracts across the client portfolio.
Client retention exceeding 99% over the past six years.
Structural Cost Advantage
Government-backed PPP delivery centres with nominal rental costs.
Average rent of approximately US$0.37 per sq. ft., compared with US$1.37 in Tier-1 cities.
Rental costs approximately 73% below Tier-1 market rates.
Long-term 5+5-year lease arrangements.
Government Incentives
Approximately US$1.1M already received under state investment-promotion policies since 2022.
A further US$1.1M in incentives committed over the next two financial years.
Capital-Light Financial Structure
Adjusted EBITDA margin of approximately 22%.
Fixed assets of only US$0.20 per US$1.00 of revenue.
Total borrowings of approximately US$0.75M.
Finance costs represent approximately 0.5% of revenue.
No working-capital debt.
Immediate Capacity for Expansion
An additional 2,000-seat campus is coming into operation.
Existing infrastructure provides immediate capacity to consolidate operations and accommodate further growth without significant additional capital investment.
Operational Resilience
Delivery centres distributed across six Indian states.
Ability to reroute operations between locations, ensuring business continuity in the event of local disruptions.
International Expansion Potential
Approximately 95% of current revenue is generated domestically.
International contracts offer significant upside through higher-margin opportunities using the existing low-cost delivery infrastructure.
Potential to serve as a ready-made India capability centre for an international strategic buyer.
Expansion into Government Services
Established e-governance practice supported by multi-year public-sector contracts.
Eligibility to participate in the majority of tenders within its operating segment.
Operations & Service Offering
The company employs approximately 4,500–4,600 billable professionals, with around 95% working on-site across its delivery centres.
Its core service portfolio includes:
Customer Experience (CX) and Customer Support.
Back-Office and Business Process Management.
E-Governance and Public-Sector Services.
The company operates a proven, human-led and technology-enabled sales platform, having secured more than 30 clients across multiple industries.
Its commercial strategy is evolving towards dedicated industry verticals, with established practices in:
Healthcare.
E-commerce.
Financial Services.
Further expansion is planned into insurance, automotive, travel, and enterprise technology.
| アドバイザー | Deals |
|---|---|
| MergersCorp M&A International | 21 |
| Keith Advisory | 17 |
| GCG | 9 |
| JP Morgan | 41 |
| Jefferies | 23 |
| Lazard | 26 |
| Goldman Sachs | 30 |
売却案件
スペインBusiness ServiceL#20261223The organization is a leading commercial…
 アメリカ合衆国Business ServiceL#20261201
An exclusive opportunity to acquire the …
 インドBusiness ServiceL#20261197
An opportunity to acquire a long-establi…
 イタリアRenewable energyL#20261228
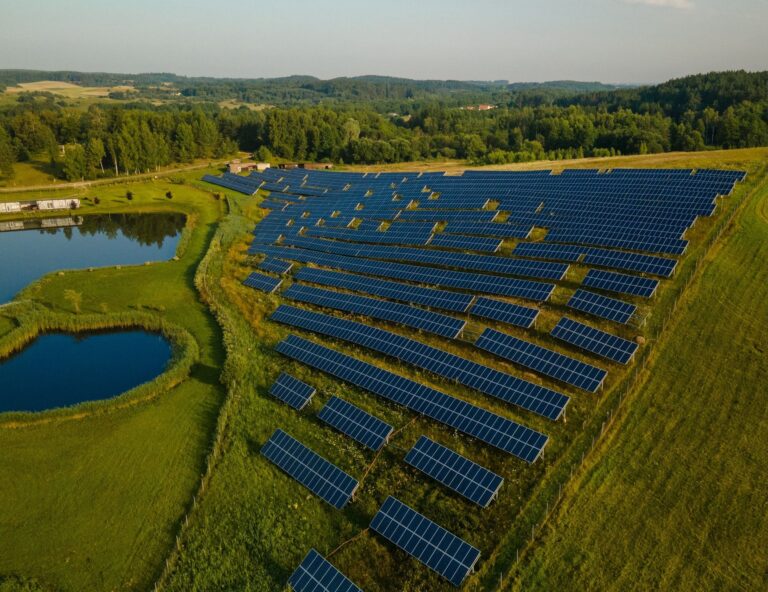
A 12.73 MWp agrivoltaic solar photovolta…
 アメリカ合衆国TechnologyL#20261226
A large-scale energy and data center dev…
 アメリカ合衆国TechnologyL#20261227
An opportunity to participate in a large…
 アメリカ合衆国TechnologyL#20261225
Astrategically positioned land and power…
 アメリカ合衆国TechnologyL#20261224
The project is structured around long-te…